 by SKJ Landbase
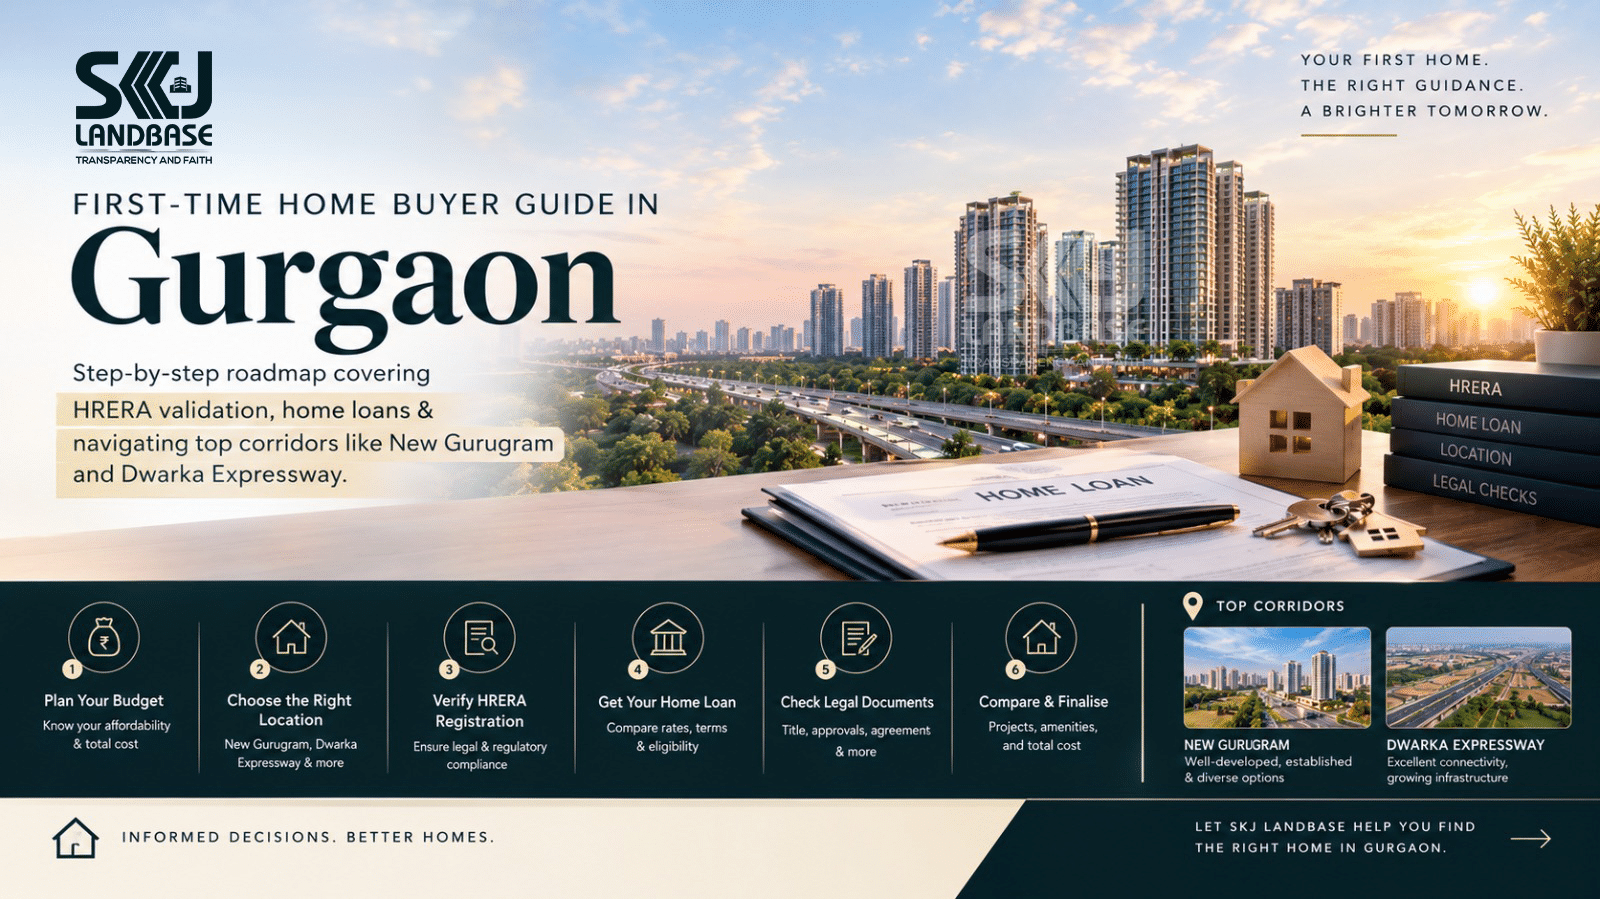
This home buyer guide Gurgaon explains how to purchase your first property with confidence, from setting your budget and checking HRERA registration to comparing home loans and choosing the right location. If you are planning to buy your first flat in Gurgaon (Gurugram), understanding the legal checks, hidden costs and available residential corridors can help you make a more informed decision.
Whether you are considering New Gurugram, Dwarka Expressway or another part of the city, this step-by-step guide covers the essentials every first-time home-buyer should know before booking a property.This first-time home buyer guide for Gurgaon explains every major step—from calculating your budget and checking HRERA registration to comparing New Gurugram and Dwarka Expressway, arranging a home loan, and completing the final paperwork.
Whether you are a salaried professional buying your first 2 BHK, a family looking for a 3 BHK, or a buyer exploring a new residential project, this road-map will help you make a more informed decision.
Quick Guide: How to Buy Your First Home in Gurgaon
| Step | What You Need to Do | Why It Matters |
|---|---|---|
| 1. Set your budget | Calculate your savings, down payment, EMI and additional costs | Prevents overborrowing |
| 2. Choose the right location | Compare New Gurugram, Dwarka Expressway and other suitable corridors | Aligns your purchase with your lifestyle |
| 3. Shortlist properties | Compare the developer, project stage, layout and amenities | Helps identify suitable options |
| 4. Verify HRERA registration | Check the exact project and phase on the official portal | Helps establish the project’s regulatory status |
| 5. Check legal documents | Review title, approvals, agreement and encumbrances | Reduces legal and ownership risks |
| 6. Arrange a home loan | Compare eligibility, interest rates, fees and loan terms | Makes financing more predictable |
| 7. Calculate the complete cost | Include taxes, registration, maintenance and other charges | Avoids last-minute financial pressure |
| 8. Inspect and complete paperwork | Verify the unit, execute documents and retain receipts | Supports a smoother purchase |
Step 1: Decide How Much Home You Can Actually Afford
Before visiting a sales office, decide your total purchase budget. A property’s advertised price is not necessarily the amount you will ultimately spend.
Your budget should include:
- The down payment or buyer’s contribution.
- Monthly home loan EMI.
- Stamp duty and registration charges, as applicable.
- GST, where applicable to the property and transaction.
- Parking, club, maintenance deposits or other contractual charges.
- Interiors, appliances, moving costs and furnishing.
- An emergency fund for unexpected expenses.
How much should you keep for a down payment?
The required contribution depends on the property’s price, the lender’s loan-to-value limits, your eligibility and the loan structure. Do not assume the bank will finance the entire purchase price or every associated charge.
For planning purposes, model several down-payment scenarios before shortlisting properties. Keep enough cash available for transaction expenses and emergencies rather than using all your savings to secure the booking.
Example: Planning the cost of a ₹1 crore home
The following illustration assumes a hypothetical loan of ₹80 lakh against a ₹1 crore property. It is not a lender quotation, an eligibility guarantee or a representation of the total acquisition cost.
| Particular | Illustrative Amount |
|---|---|
| Property price | ₹1,00,00,000 |
| Assumed home loan | ₹80,00,000 |
| Buyer’s contribution towards price | ₹20,00,000 |
| Other purchase expenses | Additional |
| Emergency savings | Keep separately |
At an illustrative interest rate of 8.5% per annum over 20 years, an ₹80 lakh loan would have an EMI of approximately ₹69,400 per month. The actual EMI will depend on the lender’s rate, tenure, disbursement and applicable terms.
The lesson is simple: evaluate the monthly payment and the cash needed upfront—not just the property price.
Step 2: Get Your Home Loan Plan Ready
A home loan can help you purchase a property without paying the entire price upfront, but your borrowing decision should be based on repayment capacity rather than the maximum amount a bank is willing to offer.
Lenders generally evaluate income, employment or business stability, existing EMIs, credit history, age, tenure and the property documents.
Documents commonly required for a home loan
| Applicant Type | Commonly Requested Documents |
|---|---|
| Salaried applicant | PAN, identity and address proof, salary slips, bank statements, Form 16 or income tax returns, as requested |
| Self-employed applicant | PAN, KYC documents, income tax returns, financial statements, business documents and bank statements |
| Property documents | Allotment letter or agreement, title documents where applicable, approved plans and other lender-required records |
| Additional documents | Own-contribution proof, co-applicant documents and information about existing loans, as applicable |
The lender may request additional documents depending on your profile and whether you are buying a new, under-construction or resale property.
Compare these five things before choosing a lender
- Interest rate: Compare the rate offered for your specific borrower profile.
- Annual Percentage Rate and fees: Read the Key Facts Statement and ask about processing, legal, valuation and other applicable charges.
- Fixed versus floating rate: Understand how the rate can change and what that could mean for your EMI or tenure.
- Prepayment conditions: Check the terms that apply to your particular loan.
- Disbursement schedule: For under-construction properties, understand when payments will be released and how interest may accrue before full disbursement.
Do not compare home loans on the advertised interest rate alone. Ask the lender for a written estimate of the complete borrowing cost.
Important: Obtain loan pre-approval or an eligibility assessment before making a substantial financial commitment. A pre-approval is not a substitute for property due diligence or final loan sanction.
Step 3: Verify the Project on HRERA Before Booking
One of the most important steps in buying a property in Gurgaon is checking the relevant registration and approvals.
The Haryana Real Estate Regulatory Authority (HRERA), also referred to as HARERA, has separate authority structures for Gurugram and the rest of Haryana. The official portals provide facilities for searching registered projects and accessing project information.
Start here:
- HRERA Gurugram: https://hareraggm.gov.in/en/
- Haryana RERA project search: https://haryanarera.gov.in/assistancecontrol/project_search_public/1
How to check a project’s HRERA registration
1. Search for the exact project name.
Use the official project-search facility. If the project has a similar name to another development, confirm the sector, promoter and address over-borrowing
2. Confirm the registration number.
Match the registration certificate with the project being marketed to you. Do not rely solely on a screenshot, brochure or salesperson’s verbal assurance.
3. Check the promoter’s details.
Confirm that the developer or promoter shown in the official records matches the entity mentioned in the transaction documents.
4. Verify the phase.
Large townships can be developed in multiple phases. Check the registration details for the specific phase you intend to buy in rather than assuming that registration of one phase automatically covers every phase.
5. Review the disclosed project information.
Check the registered address, sanctioned or disclosed details, completion timeline, status updates and other available records.
6. Investigate any discrepancy.
If the name, phase, address, registration number or completion information does not match the seller’s claims, request written clarification and obtain independent advice before proceeding.
Is HRERA registration enough to make a property safe?
No. Registration is an important regulatory check, but it is not a substitute for examining title, land rights, approvals, contractual obligations, construction status and the specific unit you are purchasing.
Under the applicable real estate law, projects generally require registration unless an exemption applies. The law includes specified exceptions, including certain small projects and projects with prior completion certificates. Verify the actual legal position for the property in question.
For an under-construction property, also review the project’s disclosed completion timeline and applicable agreement terms. For a completed or resale property, verify the relevant completion or occupation documentation and title records as applicable.
Step 4: Complete the Legal Due Diligence
Before paying a substantial booking amount or signing a binding agreement, have the documents reviewed by an independent property lawyer.
The exact records required will depend on the property, its ownership structure, project stage and applicable permissions.
Property verification checklist
- Title and ownership: Confirm the seller’s legal right to sell the property.
- Land records and title chain: Review relevant ownership documents and prior transfers.
- Encumbrances: Investigate mortgages, charges, liens, litigation or other claims where relevant.
- Approvals: Check applicable land-use permissions, sanctioned building plans and statutory approvals.
- Agreement for sale: Review the unit details, total price, payment milestones, possession terms, cancellation conditions and remedies for delay.
- Area and specifications: Confirm the carpet area, unit number, floor, parking provisions and specifications in the contract.
- Possession documentation: For completed properties, check applicable completion or occupation certificates and handover records.
- Outstanding dues: Check maintenance, utility, property tax and other payable amounts, where applicable.
For a resale home, pay particular attention to the ownership chain, existing loan or mortgage, seller’s authority, outstanding dues and the documents required for transfer.
Never rely on the developer’s reputation alone as a replacement for document verification.
Step 5: Choose the Right Location in Gurgaon
The best area to buy a home in Gurgaon depends on your workplace, family requirements, budget, commute, preferred property type and long-term plans.
New Gurugram and Dwarka Expressway are two corridors worth comparing, but they serve different buyer priorities. You should also consider established areas or other corridors if they better match your daily needs.
New Gurugram vs Dwarka Expressway
| Factor | New Gurugram | Dwarka Expressway |
|---|---|---|
| General character | Broad residential belt with a mix of established and newer developments | Residential corridor shaped by expressway connectivity and continuing urban development |
| Typical buyer consideration | Access to employment areas, established road links and a range of housing options | Connectivity towards Delhi, airport-side destinations and different parts of Gurugram |
| Property options | Multiple configurations and price points, depending on the sector and project | Apartments and other residential formats, depending on the sector and project |
| What to verify | Sector-level road access, nearby services, commute and construction status | Exact access to the expressway, service roads, junctions, commute and nearby infrastructure |
| Potential trade-off | Travel time and local infrastructure can vary considerably by sector | Access, congestion, surrounding construction and infrastructure completion can vary by location |
| Best next step | Compare the exact sector and daily travel routes | Compare the exact sector, approach road and actual journey to key destinations |
Neither corridor is automatically the better investment. Compare individual projects and actual travel routes rather than relying on the corridor name alone.
New Gurugram: Who should consider it?
New Gurugram generally refers to a broad set of developing and established residential sectors around the NH-48 and wider New Gurgaon belt. Buyers may find a range of residential communities and configurations across this area.
It may be worth exploring if you prioritize:
- Access to your workplace and regular travel routes.
- A choice of apartments and residential communities.
- Proximity to the specific schools, hospitals, shopping and daily services your family uses.
- A property that fits your budget without compromising financial stability.
Check the precise sector and surrounding infrastructure. The experience of living in one part of New Gurugram may be very different from living in another.
Dwarka Expressway: Who should consider it?
Dwarka Expressway is an important connectivity corridor linking parts of Gurugram with Delhi. Its residential market has attracted attention alongside infrastructure development and the growth of nearby sectors.
It may be worth exploring if you prioritize:
- Your regular route towards Delhi or relevant airport-side destinations.
- Access to the specific commercial or employment areas you travel to.
- A newer residential development, subject to project availability and approvals.
- A location that fits your expected commute and long-term housing needs.
Do not assume that every property marketed as being on Dwarka Expressway has the same level of access. Visit the actual site and check its approach roads, junctions, public transport availability and current surroundings.
What about Golf Course Extension Road and other corridors?
If your work, school or family routine is concentrated in southern or central Gurugram, compare Golf Course Extension Road, Southern Peripheral Road and established city locations as well.
A slightly more expensive home near your daily destinations may sometimes be more practical than a larger home that creates a longer commute. Compare total ownership cost, not just price per square foot.
Step 6: Compare Properties Using the Same Criteria
Once you shortlist a corridor, compare individual developments systematically.
| Comparison Factor | What to Check |
|---|---|
| Developer | Track record, legal entity and delivery history |
| Regulatory status | HRERA registration and relevant approvals |
| Price | Total contractual cost, not just the headline price |
| Layout | Carpet area, room sizes, ventilation and usable space |
| Construction | Current progress, workmanship and site conditions |
| Amenities | What is included, what costs extra and when it will be available |
| Connectivity | Real travel times to work, schools, hospitals and transport |
| Maintenance | Estimated recurring charges and community management |
| Possession | Contractual timeline, completion status and applicable remedies |
| Resale and rental | Local demand, competing supply and realistic costs; returns are not guaranteed |
Visit the property at different times of the day if possible. Speak with existing residents in completed communities, check the surrounding area and compare the actual unit with the advertised plan.
A show apartment or brochure can help you understand a project’s concept, but the signed documents and approved plans are what you should verify.
Step 7: Understand Stamp Duty, Registration, GST and Other Charges
First-time buyers often focus on the basic property price and overlook additional expenses.
Depending on the property and transaction, the overall cost may include:
- Stamp duty and registration charges.
- GST where legally applicable, including the distinction between eligible under-construction and completed properties.
- Legal review and documentation expenses.
- Loan processing, valuation and other lender charges.
- Maintenance deposits, club charges, parking or other contractual amounts.
- Utility connections, interiors, furnishing and moving costs.
The applicable amount depends on the transaction, property status, buyer details, current rules and the terms of the agreement. Ask for a complete written cost sheet before committing.
Do not assume that a completed property and an under-construction property have identical tax treatment. Confirm the current position with a qualified tax professional or the relevant authority.
Step 8: Understand the Agreement and Payment Schedule
Read the booking form and agreement for sale carefully before signing. If any term is unclear, obtain written clarification and independent legal advice.
Pay particular attention to:
- The agreed total consideration and additional charges.
- The payment schedule and events that trigger each installment.
- The possession date and conditions for any extension.
- The specifications and carpet area.
- Cancellation, refund and deduction provisions.
- Interest or other consequences for delayed payments.
- The process for raising defects or complaints.
- The applicable terms for possession and handover.
For an under-construction property, align the payment schedule with the contract, project status and the lender’s disbursement terms. Never rely on an informal assurance that contradicts the signed agreement.
Make payments only through traceable channels to the verified recipient and retain receipts, correspondence and signed documents.
Step 9: Inspect the Property Before Taking Possession
Before accepting handover, inspect the unit and document any issues in writing.
Check:
- Doors, windows, locks and finishes.
- Plumbing, water pressure and drainage.
- Electrical points and installations.
- Signs of seepage, dampness or visible cracks.
- Flooring, fittings and promised specifications.
- Parking allocation and access.
- Common areas and promised amenities, where applicable.
- Meter readings, keys, manuals and handover documents.
For a completed property, verify the applicable completion or occupation documentation before treating it as ready for occupation. Record outstanding defects and clarify the procedure and timeline for rectification.
For a resale property, also verify the transfer process, possession status and any outstanding payments before completing the transaction.
Common Mistakes First-Time Home-buyers Should Avoid
1. Booking before checking HRERA: Verify the exact project and phase before committing funds.
2. Stretching the budget: Leave room for additional costs, future expenses and income uncertainty.
3. Choosing a location based only on future promises: Assess existing access and infrastructure, and treat future projects as uncertain until confirmed.
4. Assuming the bank’s approval means the property is legally clear: Loan approval and independent property due diligence serve different purposes.
5. Ignoring the total cost: Compare the full cost sheet, including applicable taxes, registration and contractual charges.
6. Relying on verbal commitments: Get material promises and changes recorded in the appropriate signed documents.
7. Ignoring the resale market: Consider competing supply, the likely buyer pool and the costs of selling. Appreciation is never guaranteed.
8. Using every rupee for the down payment: Preserve an emergency reserve and budget for interiors, moving and other expenses.
How SKJ Landbase Can Help First-Time Home-buyers in Gurgaon
Finding a suitable home is not just about selecting a project with attractive amenities. It involves matching your budget, location preferences, family requirements and long-term plans with the available properties.
SKJ Landbase helps buyers explore residential options across Gurugram and compare projects based on location, configurations, developer information, amenities and purchase considerations.
For first-time home-buyers, the process can include:
- Shortlisting homes according to budget and preferred location.
- Comparing projects across New Gurugram, Dwarka Expressway and other relevant corridors.
- Understanding the differences between available configurations and project stages.
- Arranging site visits and helping buyers obtain relevant project information.
- Encouraging verification of registration, approvals and contractual details before booking.
Property-specific facts and legal documents should always be independently verified. Home loan eligibility and terms are determined by the lender, and SKJ Landbase does not replace independent legal or tax advice.
Planning to buy your first home in Gurgaon? Start with your budget, shortlist the right locations, verify the project and then compare the properties that fit your needs. A structured process can help you make a more confident and informed decision.
Sanjeev Singh, MD of SKJ Landbase says:
“Buying your first home is not just a financial milestone; it is a long-term decision that shapes your family’s lifestyle and financial security. First-time home-buyers in Gurugram should begin by understanding their budget, assessing their home loan repayment capacity, and selecting a location that suits their everyday needs.
Before booking a property, buyers must verify the project’s HRERA registration, review the relevant legal documents, understand the complete cost of ownership, and carefully examine the builder’s commitments. Locations such as New Gurugram and Dwarka Expressway offer different advantages, so the right choice should depend on connectivity, infrastructure, workplace proximity, and the buyer’s long-term requirements.
At SKJ Landbase, we believe that the right property is not necessarily the most expensive one or the one generating the most market attention. It is the property that aligns with the buyer’s budget, priorities, and future plans. A well-informed decision today can help create a more secure and comfortable tomorrow.”
For first-time home-buyers, the takeaway is clear: plan your finances, verify before you buy, compare locations carefully, and choose a home that fits your long-term goals.
Frequently Asked Questions
1. How do I buy my first home in Gurgaon?
Start by setting your budget and estimating your down payment and EMI. Shortlist locations and projects, verify the relevant HRERA registration and property documents, compare home loan offers, review the agreement and total cost, and complete the purchase only after the necessary checks.
2. How can I check HRERA registration for a Gurgaon project?
Use the official HARERA Gurugram or Haryana RERA project-search portal. Search for the exact project and confirm the registration number, promoter, address and phase against the information provided by the seller.
3. Is HRERA registration enough before buying a flat?
No. Registration is an important check, but buyers should also review title, relevant approvals, the agreement, payment terms, construction or possession status and other property-specific records.
4. How much salary do I need to buy a flat in Gurgaon?
There is no single salary requirement. It depends on the property price, down payment, loan amount, interest rate, tenure, existing debts, household expenses and lender eligibility criteria. Obtain an assessment from the lender and ensure the EMI fits your overall budget.
5. Which is better for a first-time buyer: New Gurugram or Dwarka Expressway?
It depends on your workplace, budget, daily commute and preferred property. Compare individual sectors, project approvals, road access, amenities and total cost rather than assuming either corridor is universally better.
6. What costs should I include apart from the flat price?
Potential additional costs include stamp duty, registration, applicable GST, legal and loan charges, maintenance deposits, parking or club charges, interiors and moving expenses. Ask for a written cost sheet and confirm the applicable charges for your transaction.
7. Should I buy an under-construction or ready-to-move property?
An under-construction property may offer different layouts, payment schedules and delivery risks. A completed property may allow you to inspect the actual unit and surrounding community. Compare the total price, documentation, possession status, financing and your timeline before deciding.
8. What documents should I check before paying a booking amount?
Check the project’s registration and relevant approvals, the seller’s authority, available title and land records, the booking terms, the total cost sheet and the draft agreement. Have a property lawyer review the relevant documents before making a substantial commitment.
Final takeaway
Buying your first home in Gurgaon becomes easier when you follow a clear sequence: budget first, compare locations, verify HRERA, review legal documents, arrange finance and understand the full cost before booking.